NZ IFRS 18: Statement of cash flows – interest and dividends presentation
NZ IFRS 18: Statement of cash flows – interest and dividends presentation
Under NZ IFRS 18, the primary change is that all entities will have to change the way they classify expenses in the statement of profit or loss, allocating them to one of five categories: investing, financing, income taxes, discontinued operations and operating (click here for our initial March 2025 article for further information).
Other changes that NZ IFRS 18 introduces include: (i) Aggregation and disaggregation criteria; (ii) Management-defined Performance Measures (MPMs); and (iii) Consequential changes to other areas of financial reporting.
A full list of the previous articles in our NZ IFRS 18 series is provided at the end of this article.
In this month’s article, we highlight the changes that NZ IFRS 18 introduces with respect to where cash flows related to interest and dividends are presented in the Statement of cash flows.
How does NZ IFRS 18 affect the statement of cash flows?
The introduction of NZ IFRS 18 has flow-on effects for how entities prepare their statements of cash flows. One of the main changes relates to the way interest and dividends (both received and paid) are classified, with different rules depending on whether (or not) the entity has specified main business activities (‘SMBAs’), i.e.- Investing in particular types of assets, and/or
- Providing financing to customers.
(click here for our previous article discussing SMBAs in more detail).
Entities with no SMBAs - Classification of interest and dividend cash flows
Previously, NZ IAS 7 Statement of Cash Flows (‘NZ IAS 7’) provided entities with a choice as to where to classify interest and dividends received and paid – i.e., with within operating activities, investing activities, or financing activities.However, as a result of the introduction of NZ IFRS 18, consequential amendments to NZ IAS 7 have been made that remove this choice for those entities that do not have SMBAs, as detailed in the table below.
The table below shows how the adoption of NZ IFRS 18 may change the classification of cash flows from interest and dividends for an entity without SMBAs.
|
|
Current classification |
New classification |
|---|---|---|
| Interest paid | Operating or financing | Financing |
| Interest received | Operating or investing | Investing |
| Dividends received | Operating or investing | Investing |
| Dividends paid | Operating or investing | Financing |
Important point to note/re-iterate post-NZ IFRS 18 adoption:
- Interest paid continues to be presented in the statement of cash flows within financing activities. This is irrespective of whether has been capitalised to a ‘Qualifying asset’ in accordance with NZ IAS 23 Borrowing Costs.
- Dividends paid will always be classified as cash flows from financing activities
- Interest received and Dividends received will always be classified as cash flows from investing activities.
That is, for entities with no SMBAs, there is no longer an option to present any of these items as part of operating cash flows.
Accordingly, certain restatements to the line items within an entity’s statement of cash flows may need to be made upon adoption of NZ IFRS 18.Entities with SMBAs - Classification of interest and dividend cash flows
The rules for entities with SMBAs are more complicated because they may classify interest and dividend cash flows in more than one category in the statement of profit or loss.
Entities with SMBAs typically include banks, investment companies, insurance companies, financial institutions and entities that provide financing to customers to enable customers to buy the entity’s products.
| Comment After the adoption of NZ IFRS 18, the general rule for classifying interest received and paid and dividends received is that:
|
The entity with SMBAs classifies the total of each cash flow type in a single category in the statement of profit or loss
If an entity with an SMBA classifies interest income, interest expense, and dividend income individually into a single category in the statement of profit or loss, this will determine how they are classified in the statement of cash flows.Example: If a bank applies the accounting policy available under paragraph 66 of NZ IFRS 18 and classifies all its interest expenses in the operating category in the statement of profit or loss, it must then classify all its interest paid as cash flows from operating activities.
The entity with SMBAs classifies the total of each cash flow type in multiple categories in the statement of profit or loss
Because of the general rule to classify each of interest income, interest expense and dividend income in a single category in the statement of cash flows, in circumstances where an entity with SMBAs classifies one of these in more than one category in the statement of profit or loss…(for instance, where an entity doesn’t apply the accounting policy choice available under paragraph 66 of NZ IFRS 18 and classifies interest expense between the operating category and financing category subject to the nature of the associated liability)
… the entity with SMBAs must make an accounting policy choice to classify all of the cash flows attributable to the ‘split’ profit or loss amounts in one of the applicable categories in the statement of cash flows.
Example: If a bank classifies interest expenses in both the operating category and the financing category in the statement of profit or loss, it must make an accounting policy choice to classify all its interest paid as either cash flows from operating activities or cash flows from financing activities. A similar accounting policy choice will need to be made if interest income and dividend income is recognised in more than one profit or loss category.
What’s changed for investment property entities?
Entities that invest in particular types of assets as a main business activity (for example, investment property such as commercial real estate) have a SMBA, and would account for income and expenses in the statement of profit or loss under NZ IFRS 18 as follows:- Rental income: Operating
- Fair value gains and losses on investment properties: Operating
- Interest expense on bank loans used to fund the acquisition of properties: Financing (assuming the entity does not provide financing to customers as a main business activity).
It therefore classifies all its interest paid in the statement of cash flows as financing activities.
Investment property entity - Example for interest paid
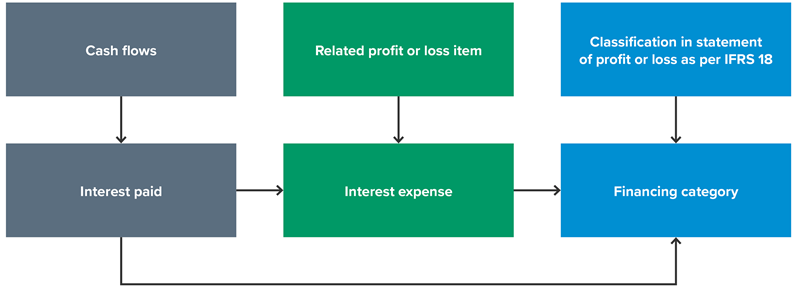
Similarly, if the investment property entity classifies interest income and dividend income in the investing category in profit or loss under NZ IFRS 18 because these items relate to assets that are not a main business activity of the investment property entity, the entity will classify those receipts as cash flows from investing activities.
What’s changed for banks?
Banks and other entities that provide financing to customers as a main business activity have a SMBA.
Interest expense for these entities for ‘Type 1 liabilities’ (i.e. liabilities that arise from transactions that involve only the raising of finance) is classified in the statement of profit or loss under NZ IFRS 18 as follows:
- If it relates to providing financing to customers: Operating
- If it does not relate to providing financing to customers: Operating to financing (depending on the entity’s accounting policy choice)
Assuming the entity chooses, or is required to, recognise interest expense across two categories in profit or loss (e.g. banks that have both Type 1 and Type 2 liabilities), it must make an accounting policy choice and select a single category for the statement of cash flows. That is, it must either classify all interest payments as cash flows from operating activities or all as cash flows from financing activities.
Banks and financial institutions - Example for interest paid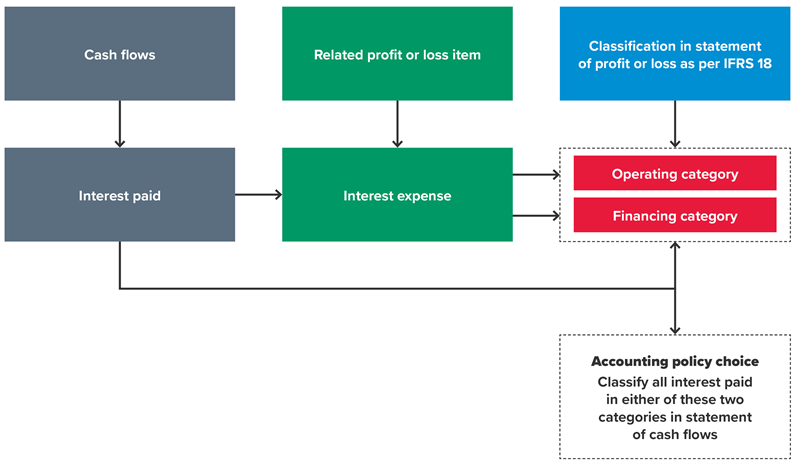
Key points
|
Changes to capitalised interest to ‘Qualifying assets’ was previously classified as cash flows from investing activities?
Entities may have historically classified interest capitalised into the carrying amount of ‘Qualifying assets’ such as self-constructed property, plant and equipment, applying NZ IAS 23 Borrowing Costs, in investing activities in the statement of cash flows. This assisted comparison to other notes in the financial statements (e.g. the ‘Additions’ line in the property, plant and equipment reconciliation table required by NZ IAS 16 Property, Plant and Equipment).
On the adoption of NZ IFRS 18, and the consequential amendments to NZ IAS 7, capitalised interest to ‘Qualifying assets’ paid can no longer be classified within cash flows from investing activities. This is because operating activities or financing activities is the only classification possibility for interest paid, depending on whether an entity has a specified main business activity of providing financing to customers and related accounting policy choices.
Why do you need to consider NZ IFRS 18 now?
| Transitioning your financial statement presentation from NZ IAS 1 to NZ IFRS 18 is not a simple exercise. NZ IFRS 18 is not just about reclassifying line items. While this may be the result, how and why an entity gets to those reclassifications is challenging because NZ IFRS 18 is a long and complex standard. Addressing the how and why involves entities making judgements regarding specified main business activities and income and expense categories. These judgements must be documented, supportable and evidenced. In addition, system changes will be required to appropriately tag expenses to the five new categories. Entities should, therefore, start their NZ IFRS 18 implementation projects now in order to be ready to retrospectively restate comparatives from 1 January 2026. Our comprehensive In Practice publication will help you on your NZ IFRS 18 implementation journey. For more details, including our ‘Six steps to a successful adoption of NZ IFRS 18’, please refer to our Adopting NZ IFRS 18 page. |
Our previous articles on our NZ IFRS 18 series
In our previous articles in our NZ IFRS 18 series, we have looked at application areas related to :
- Introduction: what will your profit or loss statement look like under NZ IFRS 18 (click here).
- What is meant by SMBA, and how entities will need to approach making this first, critical determination in applying NZ IFRS 18 (click here).
- How the new investing category in profit or loss of an entity with a SMBA differs from entities with that have no SMBA (click here).
- How the new financing category in profit or loss of an entity with a SMBA of providing financing to customers differs from other entities (click here).
- How foreign exchange gains or losses will need to be disaggregated between the three new categories to be presented in an entity’s Statement of Profit or Loss (i.e., operating, investing, financing) (click here).
- Example of how the Statement of Profit or Loss could look like for a typical retail, wholesale, manufacturer, or service business with no SMBA (click here).
- Illustrative examples: Entities that have a SMBA that is asset investment (click here).
- Illustrative examples: Entities that have a SMBA that is providing finance to customers (click here).
- How entities will be required to reassess how they aggregate, disaggregate, and label line items in the financial statements and notes (click here).
- How entities will be able to present their expenses under NZ IFRS 18, compared to the current requirements under NZ IAS 1 (click here).
- A (re)focus on Specified main business activities (click here).
- How the statement of profit or loss differs when expenses are presented by nature, function, or both (click here).
- Flexibility in classifying foreign exchange differences on intercompany loans (click here).
Need help
Please contact our Financial Reporting Advisory team for assistance in your entity’s adoption journey of NZ IFRS 18.For more on the above, please contact your local BDO representative.
This article has been based on an article that originally appeared on BDO Australia, read the original article here.